
Open interest, volume and the clearing gap
A comparison worth running:
the open interest to average daily volume ratio at three venues in the two weeks before the February 28 liquidation event.
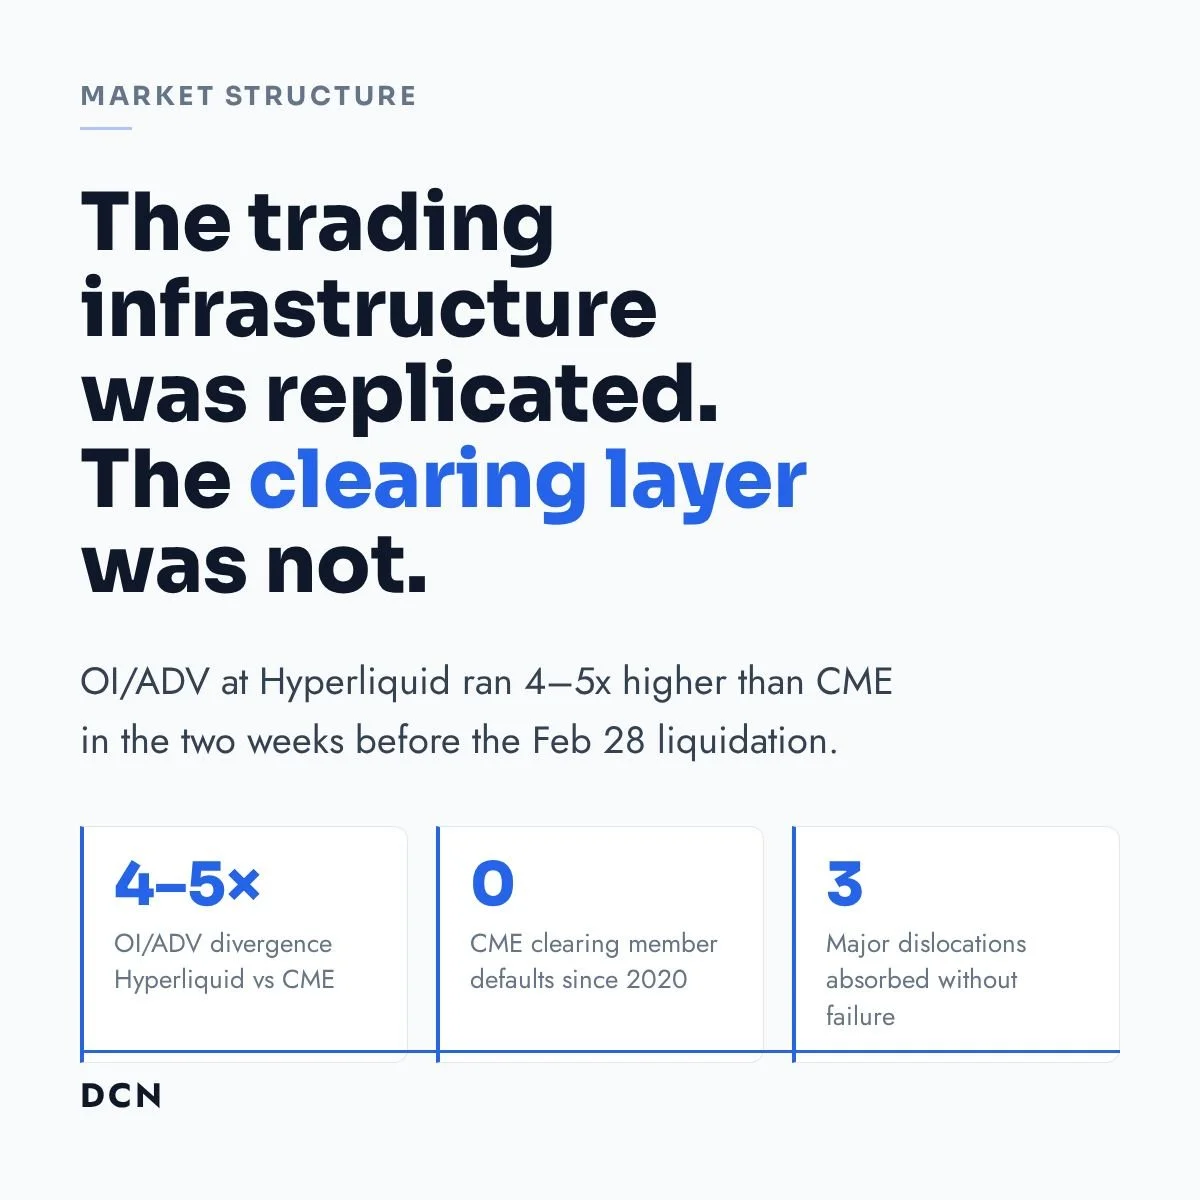
At Hyperliquid, the OI/ADV ratio for the affected perp markets was running at four to five times the equivalent ratio at CME for comparable futures products. That divergence is not a feature of market depth. It signals concentrated exposure building without the margin absorption mechanism that prevents a cascade.
CME has operated through at least three major market dislocations since 2020 without a clearing member default. The mechanism is not simply the mixed utility of its products. It is portfolio margining that includes concentration risk and a default management procedure designed and tested before the stress, not improvised during it.
The crypto market has replicated the trading infrastructure of traditional derivatives. Open interest figures, leverage mechanics, and product structure are all recognisable (mostly). The clearing layer that allowed those products to function safely at scale has not been replicated.
The OI/ADV divergence between regulated and unregulated venues is a measurable proxy for that gap. It is visible in the public data before every liquidation event.
I would be interested to know which institutional firms are incorporating multi-venue OI concentration data into their crypto derivatives risk monitoring today.
This first appeared on LinkedIn on 15 April 2026. If you want to comment or discuss, that's the place.